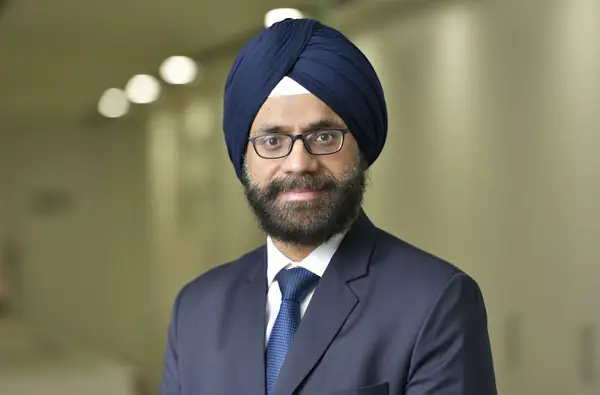
In a significant shift in India's monetary policy landscape, Puneet Pal, head of fixed income at PGIM India, has indicated that the Reserve Bank of India (RBI) is on the verge of ending its prolonged rate-cut cycle. This forecast comes amid a backdrop of persistent inflationary pressures and rising crude oil prices, which are expected to compel the central bank to raise policy rates by 50 to 75 basis points by the end of the fiscal year 2027. The implications of this shift are profound, affecting not only the broader economy but also the investment strategies of corporate and retail investors alike.
Pal's analysis highlights the dual forces at play in the Indian economy: the ongoing challenges of sticky inflation and the volatility of global crude oil prices. Over the past year, inflation has remained stubbornly above the RBI's comfort zone, driven by factors such as supply chain disruptions, elevated commodity prices, and the lingering effects of geopolitical tensions impacting oil supply. As a result, the RBI, which has maintained a historically accommodative stance to support economic recovery post-pandemic, may now be compelled to recalibrate its approach.
The anticipated rate hikes are expected to be a response to these inflationary pressures, as the RBI seeks to anchor expectations and restore price stability. Higher interest rates could serve to cool off demand, thereby alleviating some of the inflationary pressures that have been building in the economy. However, this move is not without its risks. An increase in borrowing costs could dampen consumer spending and business investments, potentially slowing down the economic recovery that has been underway since the pandemic.
For investors, Pal sees this changing landscape as an opportunity, particularly in the realm of fixed income. With yields on government bonds and corporate debt likely to rise in response to the anticipated rate hikes, there is a potential for attractive returns in high-quality corporate bonds and target-maturity funds. These investment vehicles could provide a buffer against rising interest rates, allowing investors to lock in higher yields while navigating the complexities of a shifting monetary policy environment.
Moreover, the prospect of rising yields could also lead to a reallocation of capital within the financial markets. Investors may pivot away from equities, which have been buoyed by low-interest rates, towards fixed-income securities that offer more competitive returns in a higher-rate environment. This shift could have significant implications for market dynamics, influencing everything from corporate financing costs to consumer credit availability.
In conclusion, as the RBI approaches a pivotal moment in its monetary policy, the implications of potential rate hikes extend far beyond the central bank's immediate objectives. The intersection of inflationary pressures and rising crude oil prices is setting the stage for a new chapter in India's economic narrative. For investors and policymakers alike, the coming months will be critical in determining how these factors play out in the broader economic landscape. As such, stakeholders must remain vigilant and adaptable, ready to respond to the evolving challenges and opportunities that lie ahead.